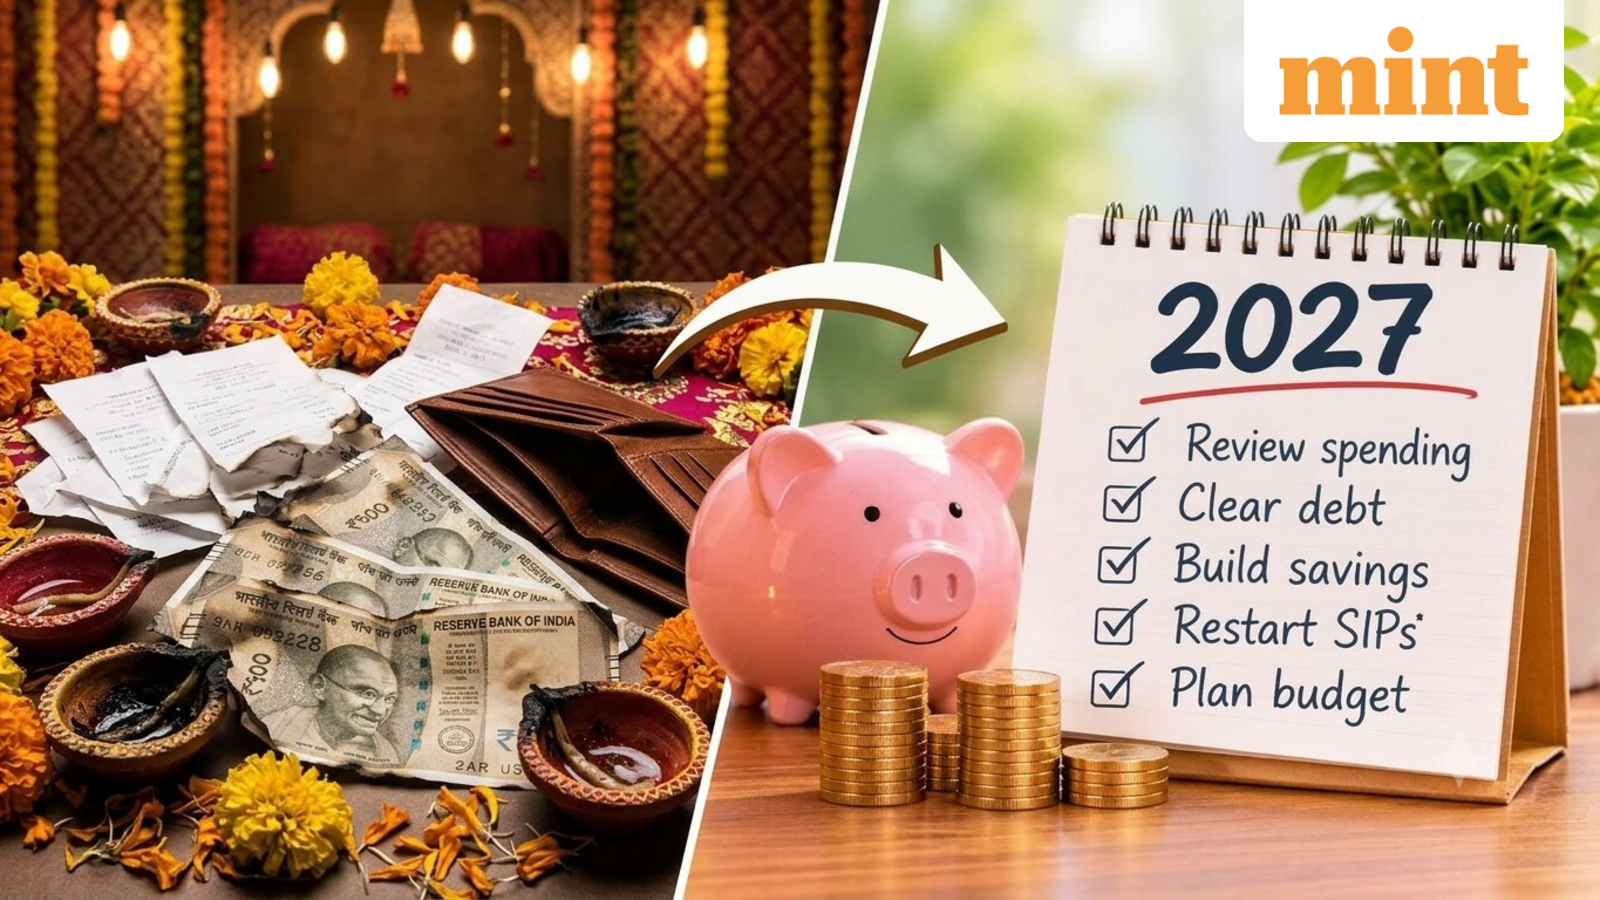
‘Burnt’ lot of money this Diwali but regretting it now? 5 smart money moves for 2027 to rebuild savings and fix finances
With the five-day Diwali festive season coming to an end on Bhai Dooj, celebrated on 11 November, many households may be reviewing the money spent on clothes, food, sweets and gifts. Some may have also relied on credit cards, EMIs or other forms of borrowing to meet their festive expenses.
As the year draws to a close, this is a good time to reassess spending, get debt under control and put savings back on track. Experts suggest 5 practical money moves to help households rebuild their finances and enter 2027 on a stronger footing.
Review festive spending
Sheersham Gupta, Director, Rupeezy, suggests reviewing bank statements, credit card bills and UPI history for October and November. Classify expenses into three categories: necessary, enjoyed and regretted.
Vedant Gupte, Co-Founder and CEO of investment platform Trackk, said the regretted category can help identify recurring money leaks, such as food delivery, quick-commerce purchases and unused subscriptions.
“Cancel subscriptions you no longer need, disable saved card details on shopping apps and review your spending for five minutes every week. This can help you identify unnecessary expenses before they add up by the end of the month.”
“To save time, you can use an AI tool like ChatGPT or Claude to do this analysis for you,” Gupta added.
Clear high-interest debt first
Gupte said credit card debt should be the first priority because it is usually the most expensive form of borrowing. Paying only the minimum amount due can keep borrowers in debt for longer and increase the overall interest burden.
List all outstanding loans and dues according to their interest rates. Direct any additional money towards the debt carrying the highest interest rate while continuing to pay the minimum on other borrowings. This approach, known as the avalanche method, can help reduce the total interest paid. Alternatively, borrowers can also consider clearing their smallest outstanding balance first, he added.
“If you can’t clear the card in two to three months, convert it into a lower-rate EMI or close it with a cheaper personal loan, and stop using the card. RBI raised the repo rate in October, and floating-rate loans could get costlier, so prepaying makes even more sense now,” Gupta added.
Rebuild emergency funds
Treat emergency savings as a fixed monthly commitment rather than setting aside whatever is left after spending. Gupta suggested allocating 15% to 20% of take-home income towards an emergency fund until it covers six months of expenses.
If this allocation is difficult initially, start with 10% and gradually increase it when an EMI ends. Keep the emergency corpus in relatively safe and accessible instruments such as liquid funds, sweep-in fixed deposits, or high-interest savings accounts. Don’t put it in equity, however good the market looks, he added.
Restart investments
If you paused your systematic investment plans (SIPs) to manage festive expenses, consider restarting them once high-interest debt is under control. Gupte said investors should not wait for the right market level to resume their investments.
“Go back to your earlier amount if your budget allows. If it feels tight, start smaller and use a step-up SIP to raise it gradually. Trying to make up for missed months with one big lump sum often backfires,” he added.
Plan a realistic 2027 budget
Gupte said a budget needs to be simple enough to follow consistently. The 50-30-20 rule can serve as a starting point, dividing income into 50% for needs, 30% for wants and 20% for savings and investments. However, households should adjust these allocations according to their income, expenses and city.
Plan ahead for festivals, weddings and holidays by setting aside a fixed amount every month in a separate savings account or fund. This can help meet next year’s festive expenses without relying on credit.
Gupta also suggested automating savings on salary day. Set up automatic transfers towards SIPs and emergency savings so that these contributions are made before discretionary spending.
Disclaimer: This is for informational purposes only. Readers should assess their financial circumstances and consult a qualified financial adviser before making investment decisions.