These 2 questions can help CA voters decide bond measures
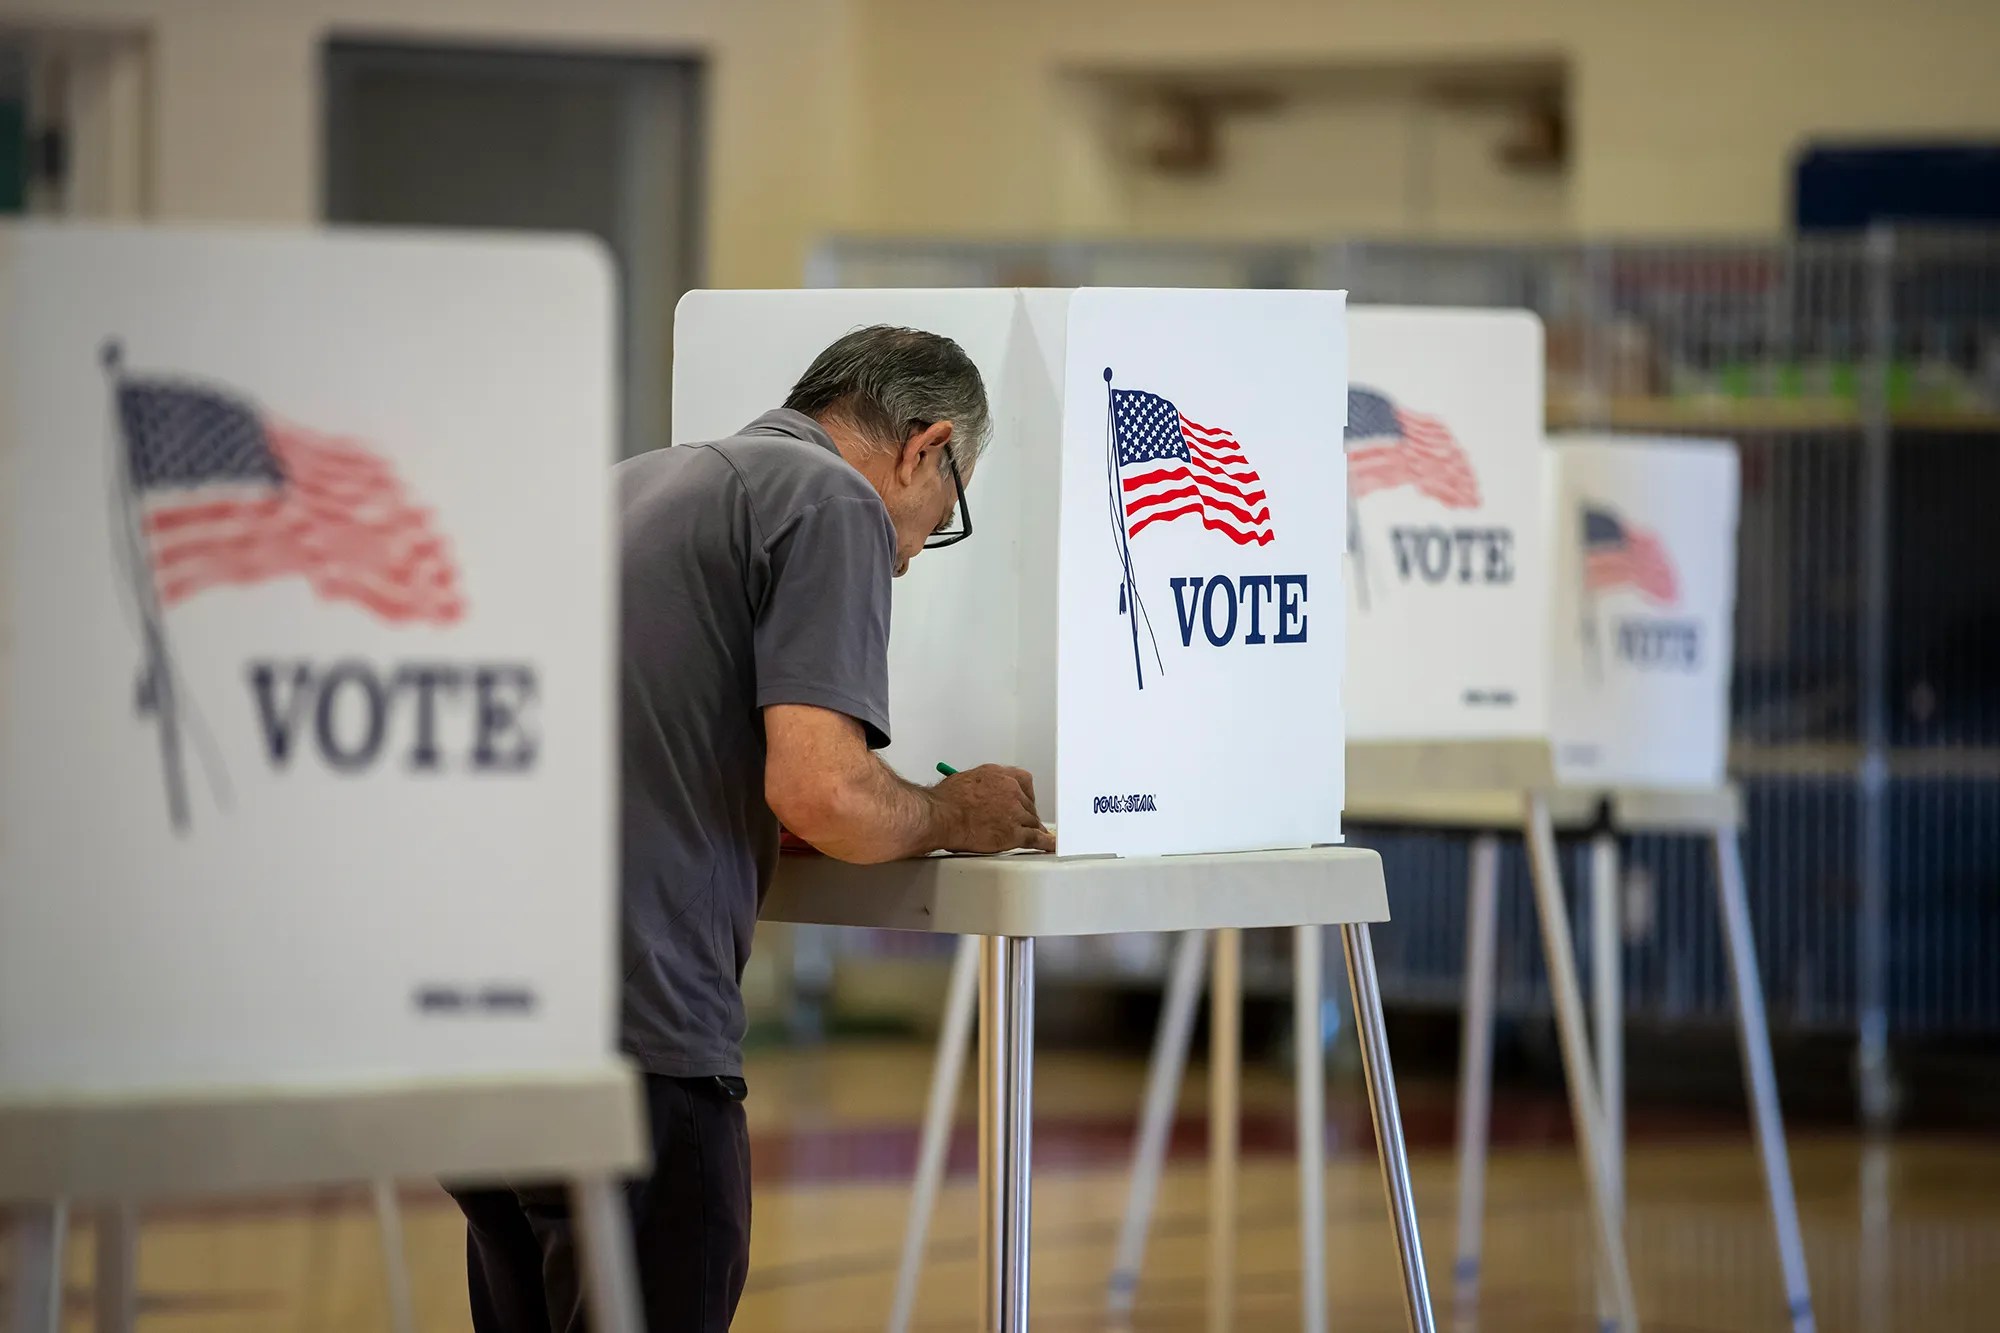
Every few years Californians are asked to approve state bonds to pay for investments like affordable housing, school upgrades, roads, water systems and other needs. This year, voters face three bond measures that would authorize billions of dollars in new borrowing.
Bonds are a useful tool for the state’s finances. They allow the government to borrow money for major projects too expensive to be financed out of the general fund and repay it with interest over several decades. This is why bonds are typically reserved for items that will last beyond the repayment period.
A 30-year bond at 4% interest costs about 15% more than paying cash, the Legislative Analyst’s Office estimates, even after inflation. The premium lets California build something now instead of saving up for it first.
California is repaying roughly $80 billion in bonds, at a cost of about $6.3 billion a year. That is around 3% of general fund revenue, below the 4% historical average.
So we are not pressed up against our borrowing limit. There’s room to issue new bonds.
But having room is not a reason to use all of it in 2026. What we commit now is money we can’t tap into later for upgrading schools and infrastructure, recovering from natural disasters or building the affordable housing we will still be short of a decade from now.
So voters must ask themselves, when is borrowing worth it?
There are two main questions to consider when evaluating bond measures: Do Californians benefit from what the money buys well after the debt is paid off? And will the investment support Californians most in need? The answers vary by bond measure.
2026 Voter Guide
Get ready for California’s midterm election. This voter guide has everything you need to know
Proposition 1, which would authorize $11.25 billion for affordable housing, targeted homeownership assistance and homelessness programs, answers yes to both questions. California faces a severe shortage of affordable housing, and Prop. 1 targets the Californians furthest from stable housing, including funding dedicated for supportive housing, farmworkers, tribal communities and young people leaving foster care.
Proposition 38 answers no to both questions. Public investment in scientific research matters, especially as the federal government is cutting vital dollars that boost California’s universities and economy. Should Prop. 38 pass, California will be making general fund debt payments in the 2050s for research work that is completed in the 2030s — without a guarantee of added public benefit.
Proposition 37, which would authorize up to $25 billion in revenue bonds that would be repaid by homebuyers — not the state — answers yes to the first question and no to the second.
Middle-income Californians really are priced out of homeownership, and this is an attempt to help more families afford a home. But the eligibility limit is 200% of area median income. For a family of four, that’s $168,850 in Fresno County, $203,150 in Los Angeles County and $375,800 Santa Clara County.
And these buyers don’t have to be purchasing their first home. Under Prop. 37, Californians who already own a house could use this state assistance to buy another, bidding against first-time buyers who have the hardest time getting in at all.
Prop. 37 also would exclusively apply toward new housing, pushing families further from job centers and adding to traffic and environmental strains. Nearly 45% of new homes built in California over the past three decades were located in wildfire-prone areas, where insurance coverage grows costlier and harder to find every year.
While Prop. 37 debt service would be outside of the general fund, the program design could be better targeted to help families struggling to afford their first home. And if voters approve Prop. 1 and Prop. 38, both measures would cost the general fund roughly $1.1 billion a year for the next 20-25 years.
Californians will have to make the call on how much the state should borrow and what investments they want to see. They also should consider what other bond financing needs may emerge in the future.
Source link