First credit card at 18: How to build a good credit score and avoid debt traps
Turning 18 brings new freedoms as well as important financial responsibilities. For many young adults, getting a first credit card may seem like a milestone in their journey towards financial independence. In India, 18 is generally the minimum legal age to hold a primary credit card, subject to the issuer’s eligibility criteria.
However, a first credit card is more than a convenient way to pay for goods and services. When used responsibly, it can help young adults begin building a credit history early. Used carelessly, it can lead to mounting debt that may take years to repay.
Understanding how credit cards work, including their costs, repayment terms and business models, is therefore essential for first-time users. Developing healthy credit habits early can help young adults build a strong credit profile and maintain long-term financial stability. Here are some key considerations.
Start small and build healthy credit habits
Raj P. Narayanam, founder and executive chairman of Zaggle, emphasised the importance of starting small and developing disciplined spending habits.
“Your first credit card is your entry point into the formal credit ecosystem, use it well and it opens every financial door ahead of you. Spend confidently across categories you already budget for, pay your dues on time every month and let your card work consistently for you,” he said.
He added, “Zaggle, with zagg.money, we see young borrowers build strong credit profiles within 12 months simply through disciplined, regular card usage. The habit you form on your first card follows you for decades. Start right.”
Zagg.money is Zaggle’s consumer payments and credit card platform.
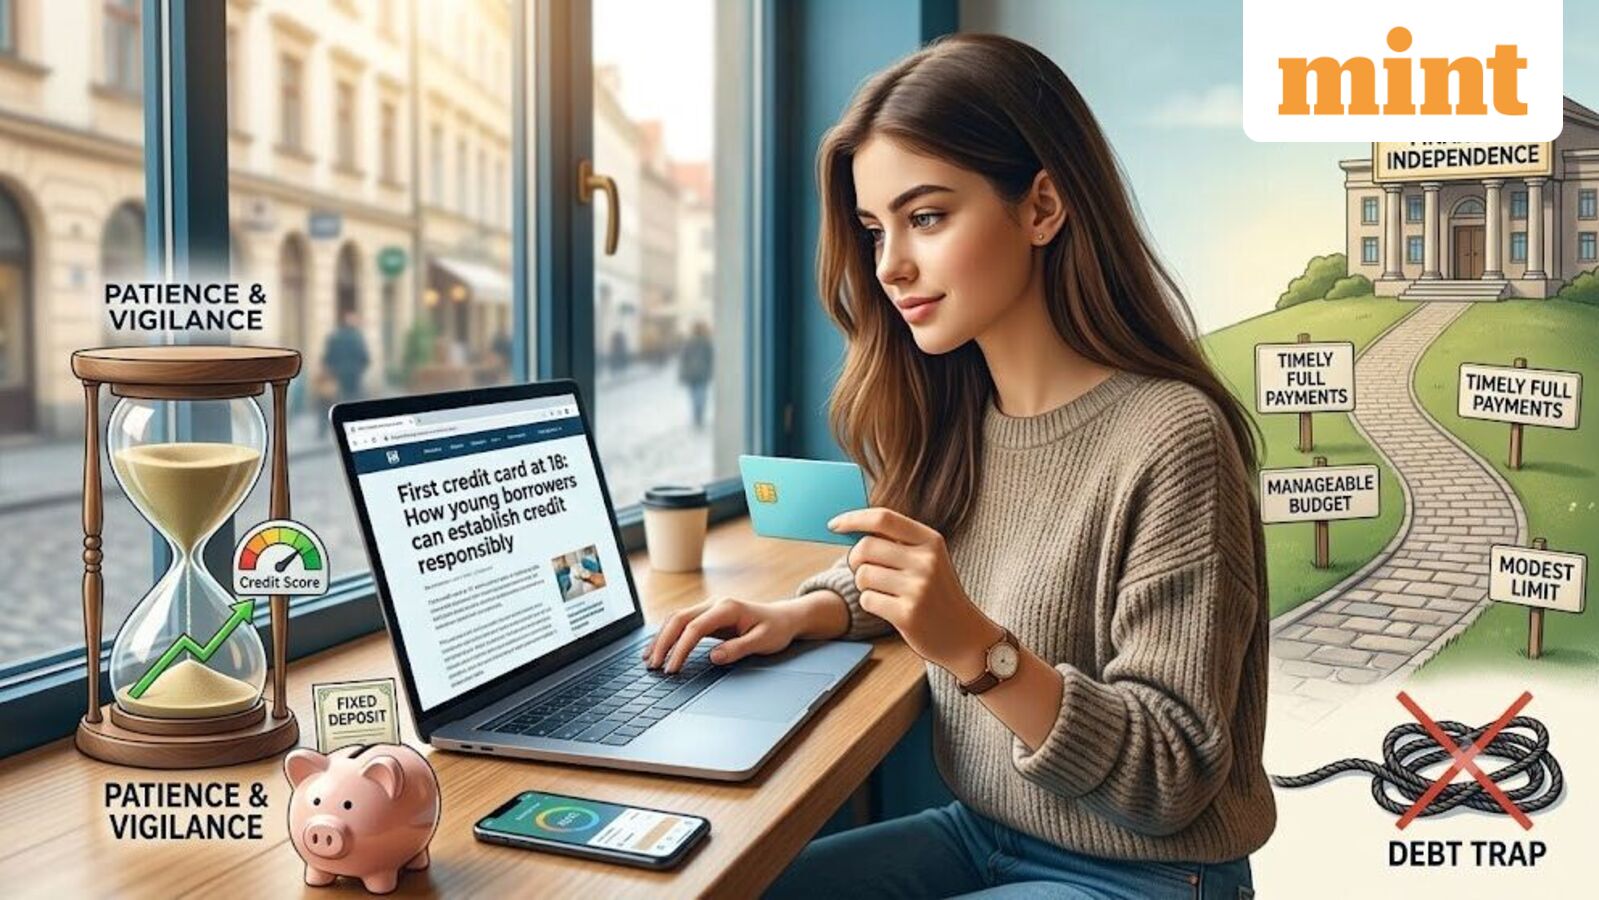
Therefore, for first-time borrowers, the key is to ensure they stay within a manageable budget and clear the entire outstanding balance by the due date. This is vital because paying only the ‘minimum amount due’ can result in a credit card user silently accumulating interest on unpaid balances. Young applicants who currently lack an independent source of income or employment can also consider a secured credit card backed by a fixed deposit, subject to the issuer’s eligibility rules.
Avoid debt traps and protect your credit score
Kapil Makhija, founder and COO of MinEMI.ai, highlighted the importance of avoiding debt traps and protecting one’s credit score to maintain a healthy relationship with lenders.
“At MinEMI we meet the other end of this story every day: people in their thirties still carrying the damage of credit mistakes made at 20. So my advice to an 18-year-old is simple. Start with one card, ideally a secured card against a small fixed deposit if you have no income yet. Set autopay for the full amount, never the minimum due, because the minimum due is how the debt trap begins,” he said.
He also advised young cardholders to keep credit utilisation below 30% of their limit, while ensuring that their spending remains affordable relative to their income.
“And never close this first card later, since your oldest account is what gives your score its depth. Built this way, a credit card at 18 is an asset,” he added.
For young adults, the broader lesson is that starting early helps only when it is accompanied by financial discipline and a long-term approach to money management. Keeping spending modest, paying bills in full and on time, and monitoring credit utilisation can help establish a positive credit history without allowing debt to undermine financial independence.
Disclaimer: Credit card eligibility, fees and terms vary by issuer. Responsible usage can help build a credit history, but credit scores are not guaranteed. Assess your repayment capacity and consult a certified financial advisor before applying for a credit card.