UPI: The small fee raising big questions for India’s payments revolution
The charge will not apply to all UPI payments.
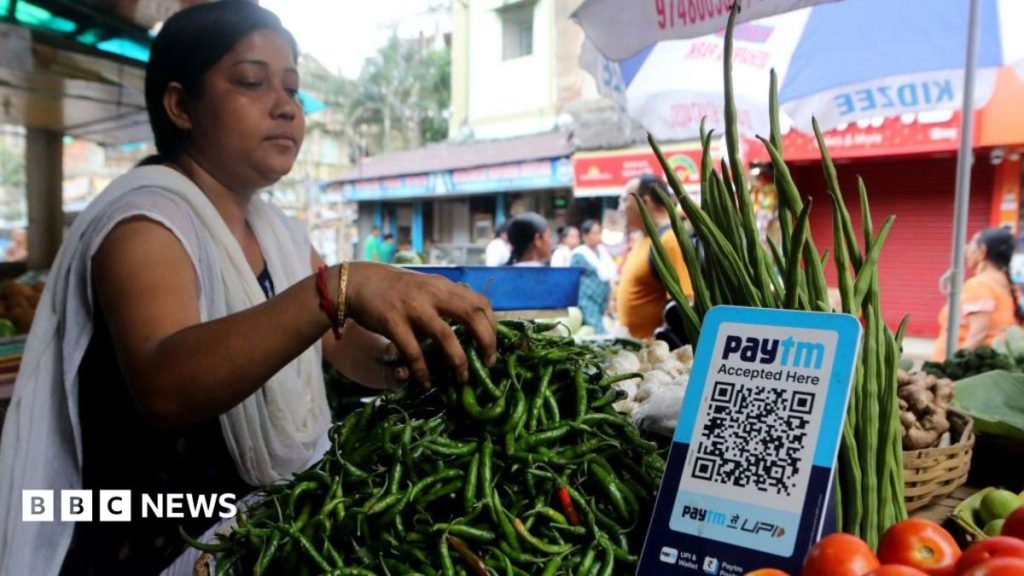
Person-to-person transfers will remain free, regardless of the amount. Payments of up to 2,000 rupees made to merchants will also remain free. Merchant payments through QR codes in rural and semi-urban areas will not attract MDR either.
The government said “approximately 96% of person-to-merchant transactions will remain unaffected”, either because they are below the threshold or because they are covered by the zero-MDR framework for small merchants.
Certain merchant payments above 2,000 rupees, including those for railways, telecom services, insurance, fuel and agricultural inputs, will instead attract a flat charge of five rupees.
For other transactions above 2,000 rupees that are subject to MDR, the fee will be 0.4% and capped at 300 rupees per transaction. The cap applies to transactions of 75,000 rupees or more.
The regulator has said the money will support investment in areas including payment infrastructure, resilience, innovation and cyber security.
The decision has sparked debate in India.
Some social media users have said charging merchants could weaken one of UPI’s biggest attractions – that it has been free to use. Others have warned that some merchants could turn to cash for larger transactions rather than absorb a fee they did not previously have to pay.
Krishnamurthy Subramanian, a former chief economic adviser to the Indian government, said the economics of a system such as UPI cannot be “evaluated using private cost versus private benefit”.
Speaking to news channel CNN-News18, Indian entrepreneur and former managing director and co-founder of fintech platform BharatPe, Ashneer Grover said that there can be a possibility where “a shopkeeper could simply refuse to accept a UPI payment of 2,000 rupees and ask you to pay entirely in cash. Then you will go back to using cash”.
The Retailers Association of India (RAI) has said that the charge could “undo years of progress in digital payment adoption among India’s smallest retailers”.
“During the festive season, a large share of transactions crosses the 2,000 rupees mark, and the moment a fee attaches itself to digital payment, cash becomes the path of least resistance,” Kumar Rajagopalan, the association’s CEO said.
Others argue that a fee is needed to help fund and expand the payments system.
“When government funds the subsidies paid for UPI, that amount comes from tax payers’ pocket. Moving to market-linked pricing mechanism removes this tax burden and directly links the cost to large businesses which benefit from UPI,” said Bipin Preet Singh, CEO of fintech firm MobiKwik.
Since its launch a decade ago, UPI has become a central part of India’s digital payments economy. In August, UPI processed a record 24.51 billion transactions worth 29.82 trillion rupees (roughly $311bn), according to NPCI data.
The question now is whether the new charges will change how businesses use UPI, particularly for larger payments.