We’re upgrading our Goldman Sachs rating after a strong quarter bodes well for the future
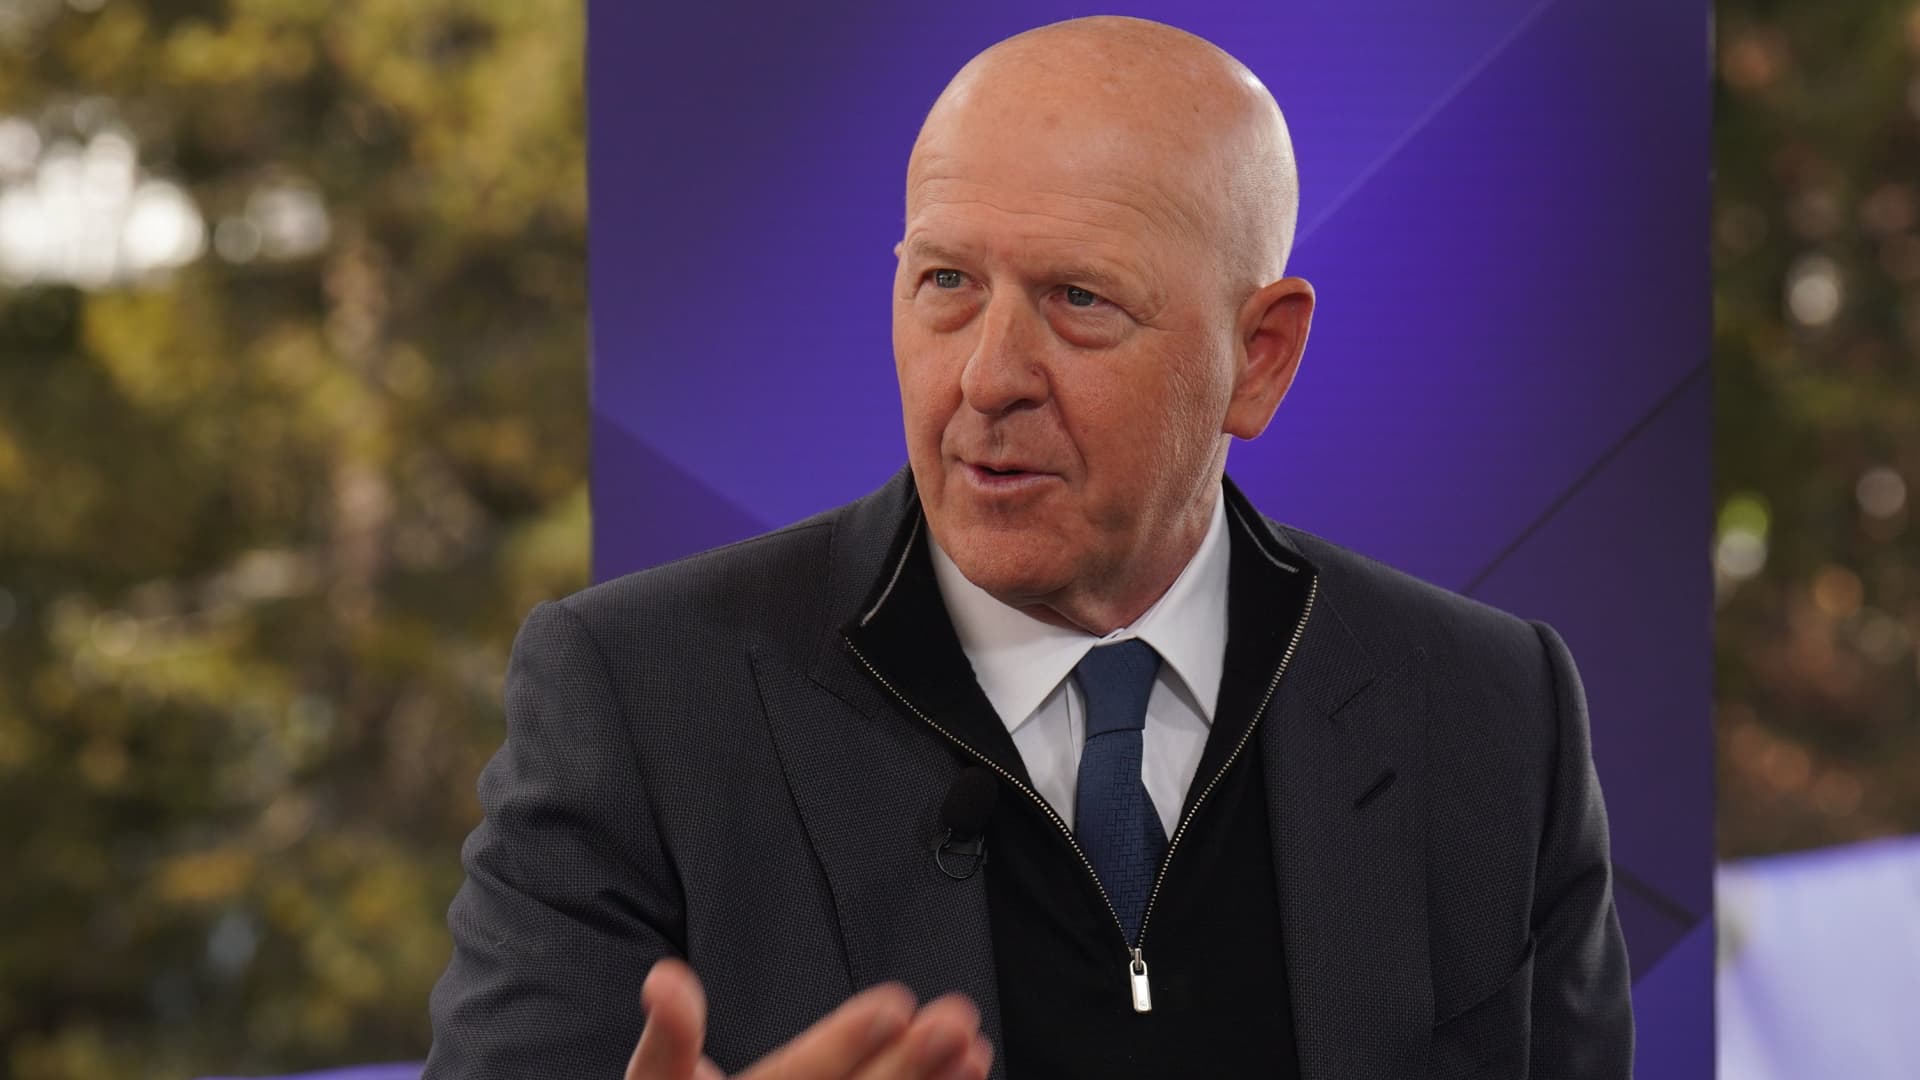
Goldman Sachs on Tuesday reported a strong quarter that should help stem the stock’s brutal decline since the summer. Revenue in the third quarter rose 23% year over year to $18.68 billion, the second-highest in company history and well ahead of the $16.71 billion consensus, according to the analyst estimates compiled by data provider LSEG. Earnings per share (EPS) in the three months ended in September surged 39% to $17.01, also a huge beat versus the $13.02 per share consensus, according to LSEG data. GS YTD mountain Goldman Sachs YTD Shares of Goldman were up more than 4% shortly after the open before giving up much of those gains. We think the quarter was strong enough to justify stepping in to take advantage of the weakness since the stock’s record-high close of $1,152 on July 15. However, material upside from here likely has more to do with the Iran war, U.S. interest rate dynamics, and the pace of AI funding than anything fundamentally going on at the bank. From an execution perspective, Goldman appears to be firing on all cylinders. Bottom line The strong showing from Goldman Sachs would have looked even better if not for the impact of an accelerated charitable contribution made in the quarter, which weighed on earnings and return on equity results. The bread-winning Global Banking & Markets division delivered strong results, which was very much behind the relatively positive reaction in the stock. This group houses investment banking, which should see a nice boost from the upcoming Anthropic initial public offering (IPO). “Our investment banking backlog remains very robust as strong revenue realizations and advisory were largely offset by solid replenishment and equity underwriting,” CFO Denis Coleman said on the post-earnings conference call. In a business that requires constant replenishment, those “strong revenue realizations” were referencing the June IPO of SpaceX , which Goldman co-led, as well as the firm’s work on Alphabet’s enormous secondary stock sale, also in June, and the $67 billion NextEra and Dominion Energy merger, which was announced in May. A nice showing in Asset & Wealth Management has demonstrated that the world’s premier investment bank can also make a lot of money away from initial public offerings (IPOs) and mergers and acquisitions (M & A). More broadly, Goldman CEO David Solomon spent time on the call talking about the importance of artificial intelligence — both the benefits and the risks to business at the bank. “In our conversations with clients, demand for compute significantly exceeds supply at the moment, creating opportunities to help develop financing structures to meet that capacity shortfall. Our differentiated financing, distribution, and investing capabilities position us to play a meaningful role in the mobilization of capital and supporting client activity.” He added, “As we support our clients, we are highly selective about the risk we underwrite and the capital we commit, particularly as client financing needs become larger and more complex.” Goldman was named as one of the six financial institutions partnering with Nvidia on AI infrastructure financing. “Beyond these financial risks, we also recognize the broader concerns around the accelerating pace of AI technology and the unchecked advancement of frontier models. … However, the choice is not between halting progress and moving forward without guardrails. We must enable innovation and also demand responsibility,” Solomon stressed, siding with Nvidia CEO Jensen Huang in the AI safety debate, which was sparked in earnest by Anthropic CEO Dario Amodei’s September “We Must Pace the Frontier” essay. Huang also said both innovation and safety are needed and that new regulation is not — views also shared by Jim Cramer. Considering Goldman’s opportunities in AI financing, as well as investment banking and other parts of its vast empire, we continue to view the stock as the best one to own within the broader financial sector. While reiterating our $1,200 price target, we’re upgrading shares to our buy-equivalent 1 rating in recognition of the favorable risk/reward setup at current levels. Segment commentary Goldman’s Global Banking & Markets division was the standout, with revenue rising over 30% year over year to $13.46 billion, more than $1.5 billion ahead of the consensus and the main driver of the overall quarterly revenue beat. Within the segment, Investment Banking revenue totaled $3.2 billion, a 21% increase versus the year-ago period and ahead of the $2.7 billion consensus. Equities revenue surged 72% to $6.44 billion, smashing expectations of $5.05 billion. Fixed income, Currency, & Commodities (FICC) revenue fell 1% year-over-year to $3.47 billion, missing expectations of $3.7 billion. In the Asset & wealth management (AWM) segment, revenue of $5.05 billion beat the $4.67 billion consensus. Compared with a year ago, revenue was up about 14%. While revenues generated here pale in comparison to the banking and markets division, it is important to the bank’s performance throughout the economic cycle. The AWM revenue streams tend to be recurring rather than episodic (like those of investment banking and trading), because most of the revenue coming from this division is based on a percentage of the firm’s assets under management. So, the more money that Goldman oversees, the better. On that note, assets under supervision (AUS) ended the quarter at a record $4.1 trillion, marking the 35th consecutive quarter of long-term fee-based net inflows. On the call, Solomon said, “For 2026, wealth management long-term net inflows are annualizing at 12%, well ahead of our 5% target, which underscores the strength of our client relationships built on trust and long-term performance.” Platform Solutions , which is Goldman’s third and final reporting segment, is tiny and no longer core to the investment story. Revenue totaled $170 million, down over 70% from the year-ago period. The decline primarily reflects Goldman’s sale of its Apple credit card business to JPMorgan. Key metrics When thinking about how to value Goldman as a financial firm, there was a lot to like this quarter. Tangible Book Value Per Share (TBVPS) – the primary basis for bank valuations, aside from EPS — came in ahead of expectations. Return on Tangible Common Equity (ROTCE), which helps investors determine the appropriate multiple to put on the metric of choice, was materially better than expected, and would have been even more so, if not for that aforementioned charitable contribution dynamic. Common Equity Tier 1 (CET1) Ratio was a tad lower than expected. However, it was still a full percentage point ahead of the required minimum, indicating plenty of excess capital with which to invest in growth and return cash to shareholders. (Speaking of capital returns, Goldman returned $3 billion via stock buybacks and another $1.49 billion via common stock dividends.) Jim Cramer’s Charitable Trust is long GS, NVDA. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.