Nikkei Surges 2,203 Points as Micron Outlook Revives AI Trade
TOKYO –
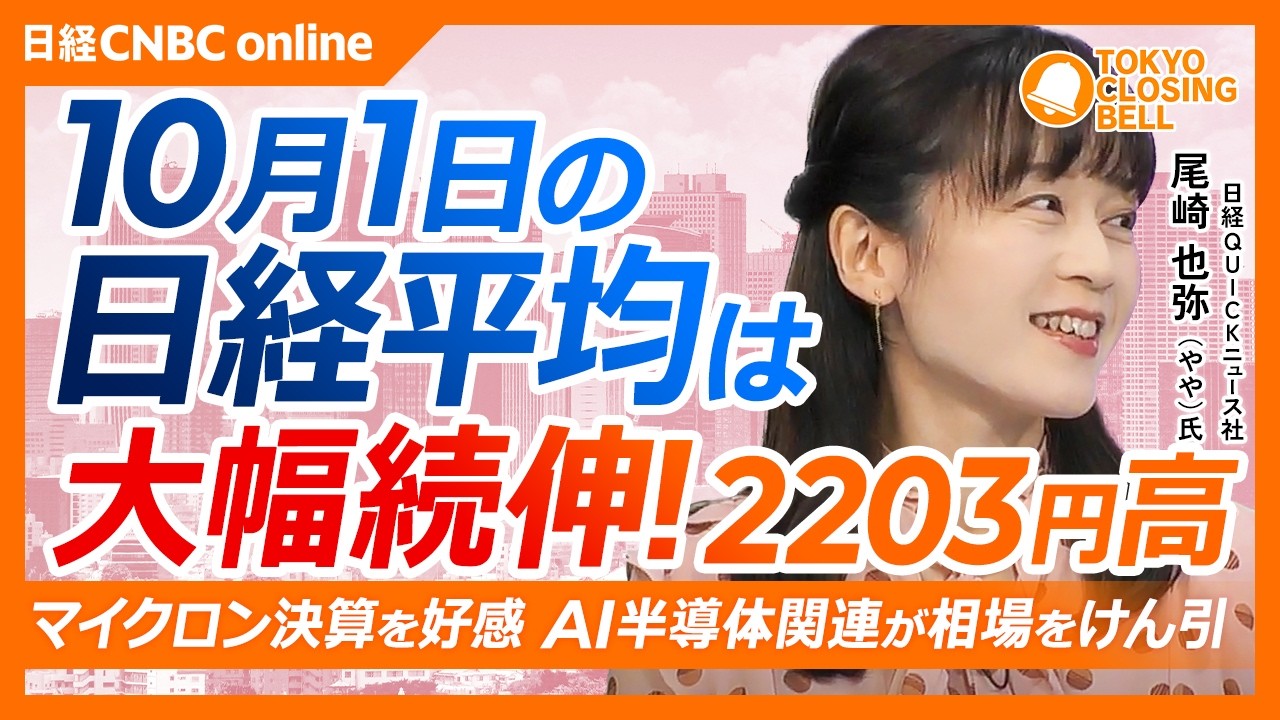
Tokyo stocks surged on October 1, with the Nikkei 225 closing at 68,957, up 2,203 points, as investors rushed back into artificial intelligence and semiconductor-related shares after Micron Technology’s strong earnings outlook reinforced confidence in global chip demand.
The rally lifted the Nikkei above 68,000 for the first time in about six weeks and marked one of the sharpest rebounds of the recent AI-driven market cycle. The move followed a strong September 30 rally, extending the market’s recovery from the ex-dividend decline earlier in the week.
The broader market was much less powerful than the Nikkei. TOPIX lagged as banks, insurers, trading houses and other value shares came under pressure, showing that the day’s advance was heavily concentrated in high-priced technology and semiconductor names.
The Nikkei opened higher at 67,107 and quickly accelerated as investors bought chip-related shares. By late morning, the index was above 68,000, and buying continued through much of the session as the market followed the lead from U.S. technology stocks and Micron’s upbeat outlook.
The day’s move reversed the caution that had dominated September 28 and September 29, when investors took profits after the Nikkei briefly topped 67,000 and then faced the mechanical drag from the September-end ex-dividend adjustment.
The October 1 rally was different in scale. It was driven by renewed confidence that AI-related demand remains strong enough to support earnings across the global semiconductor chain, from memory chips to testing equipment, manufacturing tools, electronic components and data-center infrastructure.
Micron Technology was the main catalyst. The U.S. memory-chip maker reported strong results and gave an outlook that exceeded market expectations, reinforcing the view that AI servers, high-bandwidth memory and data-center investment continue to drive demand.
That directly supported Japanese names tied to memory, chip equipment and AI infrastructure. Investors treated the Micron news as confirmation that the AI cycle still has earnings power, not just market enthusiasm.
Advantest was one of the most important drivers of the Nikkei’s rise. The chip-testing equipment maker remains one of Japan’s clearest beneficiaries of advanced AI processor demand and high-performance computing investment.
Because of its heavy weighting in the price-weighted Nikkei, Advantest can move the headline index sharply. Its strength on October 1 helped explain why the Nikkei surged even though the broader market was far more mixed.
Tokyo Electron also rose strongly. The semiconductor-equipment maker remains central to Japan’s role in global chip manufacturing and continues to benefit when investors become more confident about capital spending by semiconductor producers.
SoftBank Group was another major support. The company remains Tokyo’s most visible proxy for global AI investment through its exposure to OpenAI, Arm, robotics, digital infrastructure and other large-scale technology platforms.
SoftBank’s gain showed that investors were again willing to buy long-duration AI growth exposure, even with global bond yields still high. That was an important change from late September, when rising yields and funding concerns had kept investors more cautious toward the stock.
Kioxia Holdings also drew attention after Micron’s results strengthened confidence in the memory cycle. Kioxia remains one of Tokyo’s key gauges of demand for high-bandwidth memory, AI servers and data-center storage.
The memory theme has been volatile since July, but the October 1 session showed that investors still see Kioxia as a major beneficiary when global AI hardware demand improves.
Ibiden, Lasertec, Screen Holdings, SUMCO, Murata Manufacturing, TDK, Taiyo Yuden, Fujikura, Furukawa Electric and Sumitomo Electric also remained central to the day’s market story. These companies cover advanced substrates, semiconductor equipment, wafers, electronic components, optical fiber, cables and data-center infrastructure.
The strength in these names showed that investors were again buying the full AI supply chain, not only a handful of headline chip stocks. Still, the market’s concentration remained clear: the Nikkei surged because a small number of high-impact AI and semiconductor shares rose sharply.
The divergence with TOPIX was important. While the Nikkei rallied more than 3%, the broader index struggled because financials, trading houses and other value sectors weakened. That meant the market was not making a broad risk-on move across all sectors.
Banks and insurers were under pressure as bond-market volatility and profit-taking weighed on recent winners. Financial shares had been supported by expectations for higher Japanese interest rates, but investors rotated away from them on October 1 as money moved back into AI and semiconductor shares.
Mitsubishi UFJ Financial Group, Sumitomo Mitsui Financial Group, Mizuho Financial Group, Resona Holdings, Tokio Marine and other financial names remain important gauges of the higher-rate trade. Their weakness showed that investors were shifting from dividend and rate-sensitive value shares into growth and technology.
Trading houses also faced selling. Mitsubishi Corp., Mitsui & Co., Itochu, Sumitomo Corp. and Marubeni had been important value and shareholder-return plays, but they lagged as investors concentrated on AI-related momentum.
Pharmaceuticals and some defensive shares were also weak. That suggested investors were moving away from safety and income themes and back into growth sectors linked to U.S. technology demand.
The Bank of Japan’s Tankan survey added another layer to the market. Business confidence improved to its strongest level in eight years, supported by firm corporate earnings, price increases and resilience in parts of the manufacturing sector.
The Tankan result strengthened the argument that Japan’s economy remains resilient enough for the BOJ to continue normalizing monetary policy. That is positive for the long-term Japan investment story, but it also keeps rate-hike pressure alive.
The BOJ raised its policy rate to 1.25% on September 18, the highest level in 31 years. Markets are now focused on whether the central bank will raise rates again in December or early 2027.
The Tankan makes that question more urgent. Stronger business confidence gives Governor Kazuo Ueda more evidence that companies can withstand higher borrowing costs, but the BOJ must still avoid destabilizing the yen, bond market or equities.
Japanese government bond yields remain a major risk. Global bond markets remained under pressure on October 1, and yields in Japan have climbed to multi-decade highs. The 10-year JGB yield recently moved above 3%, a level not seen since 1996.
Higher yields are a mixed force. They support banks and insurers by improving lending margins and investment returns, but they pressure high-valuation growth shares by raising the discount rate applied to future earnings.
On October 1, the AI earnings story was strong enough to overcome the yield risk for technology shares. But if JGB yields rise again, the same semiconductor names that led the rally could become vulnerable to valuation pressure.
Higher yields also increase the government’s debt-servicing burden. Prime Minister Sanae Takaichi’s administration is trying to support households, increase defense spending and fund long-term strategic investment while maintaining fiscal credibility.
The government’s growth strategy targets large-scale public and private investment through fiscal 2040 in semiconductors, artificial intelligence, energy security, defense, shipbuilding, robotics, space and other strategic sectors.
That strategy supports many of the companies that rose on October 1, including chip-equipment makers, electronic-component suppliers, optical-network companies, power-system firms and data-center infrastructure providers.
However, higher interest rates make the funding question more difficult. Investors want evidence that Japan can support household relief and industrial policy without undermining confidence in public finances.
The yen remained weak, trading around 158 to the dollar. That supported exporters and helped the Nikkei, but it also kept imported-inflation and intervention risks alive.
A weak yen helps automakers, machinery makers, electronics companies and precision-equipment manufacturers by increasing the yen value of overseas earnings. It also supports many Nikkei heavyweights with large overseas revenue exposure.
For households and importers, however, yen weakness is a burden. It raises the cost of energy, food, raw materials and consumer goods, adding pressure to daily expenses.
The BOJ’s September rate hike has not decisively strengthened the yen because the interest-rate gap between Japan and the United States remains wide. The Federal Reserve’s policy path is therefore still central to Japan’s currency outlook.
U.S. inflation data eased some concern about an October Fed rate hike, and New York Fed President John Williams said there was no urgency for further action. That helped support U.S. technology shares and reduced some pressure on global growth stocks.
However, U.S. Treasury yields remained high, limiting the benefit. The global bond market remains tense because investors are still concerned about inflation, government borrowing and the cost of financing large deficits.
For Japan, high U.S. yields keep the dollar supported. That makes it harder for the yen to strengthen, even after the BOJ has begun raising rates.
Oil prices remained another key variable. Lower crude in recent sessions has helped sentiment, but energy costs are still high enough to affect Japan’s trade balance, corporate margins and household budgets.
Japan imports most of its energy, so oil prices feed directly into gasoline, electricity, aviation fuel, shipping, logistics, chemicals and manufacturing. If crude rises while the yen stays near 158, inflation pressure could return quickly.
Households remain under pressure despite improving wages. Consumers continue to face high costs for groceries, gasoline, electricity, transport and services.
The Tankan showed corporate confidence is strong, but households judge the economy differently. For consumers, the main issue remains whether wage gains can cover everyday costs.
Companies are still deciding how much of higher labor, logistics, materials, energy and borrowing costs can be passed on to customers. Firms with pricing power, strong brands, stable demand or exposure to long-term investment remain better positioned.
Companies without pricing power face a more difficult environment. If the yen weakens further, oil rises or consumers resist price increases, profit margins could come under pressure even when sales appear stable.
The October 1 rally therefore had two sides. The AI and semiconductor story was extremely strong, but the broader domestic economy still faces pressure from prices, yields and currency volatility.
The market’s breadth was also a warning sign. A durable rally would need stronger participation from banks, trading houses, autos, industrials, retailers and domestic-demand shares. On October 1, the rally was led mainly by AI and semiconductor shares.
The Nikkei’s technical picture improved sharply. The index not only reclaimed 67,000 but also moved through 68,000, reversing the failed breakout seen on September 28.
The next major test is whether the Nikkei can hold the 68,000 level. A sustained move above that area would signal that the AI-led rebound has regained force. A quick reversal would suggest that the market remains dependent on short-term momentum in a small number of heavyweight names.
The 67,000 level now becomes initial support. The Nikkei failed there earlier in the week, so holding above it would strengthen confidence in the rebound.
TOPIX remains the key confirmation signal. If TOPIX begins to rise alongside the Nikkei, the rally will look healthier. If TOPIX continues to lag or fall, investors may conclude that the advance is too narrow.
The Growth Market 250 Index also remains worth watching. Smaller growth shares are still sensitive to higher yields, and their performance will show whether risk appetite is broadening beyond large-cap AI names.
South Korean and Taiwanese markets will remain important for Tokyo’s chip complex. Overseas investors increasingly treat Japanese semiconductor equipment makers, South Korean memory producers, Taiwanese foundries and U.S. AI shares as one connected technology trade.
Strong South Korean semiconductor exports and firm memory demand would support Kioxia, Tokyo Electron, Advantest and related Japanese names. Weakness in Samsung Electronics, SK Hynix or Taiwan Semiconductor Manufacturing Co. would quickly affect sentiment in Tokyo.
SoftBank’s role also remains central. If investors continue to buy AI platforms, Arm-related exposure and large-scale data-center investment, SoftBank could remain a major Nikkei support. If funding costs or power-supply concerns return, the stock could again become a drag.
What to watch next: whether the Nikkei can hold above 68,000, whether TOPIX catches up, and whether semiconductor buying broadens beyond Advantest, Tokyo Electron and SoftBank Group.
Investors will monitor Kioxia, Ibiden, Lasertec, Screen Holdings, SUMCO, Murata Manufacturing, TDK, Taiyo Yuden, Fujikura, Furukawa Electric and Sumitomo Electric for signs that the AI supply-chain rally has depth.
Banks and insurers will also remain important. If financials stabilize while technology shares stay firm, the market could build a stronger base. If banks continue falling, TOPIX may struggle even if the Nikkei rises.
The yen near 158 to the dollar remains the most important domestic signal. Further weakness toward 160 would support exporters but revive inflation and intervention concerns. A rebound toward 153 would ease import costs but could pressure exporters and carry trades.
JGB yields are the second key signal. A stable bond market would help equities, while another rise in 10-year or super-long yields would pressure valuations and fiscal policy.
Oil prices are the third signal. Lower crude would help households and companies, while a renewed rise would intensify pressure on Japan’s trade balance and inflation outlook.
October 1 showed that the AI trade remains powerful enough to lift the Nikkei by more than 2,000 points in a single session. Micron’s outlook revived confidence in memory and chip demand, and Japanese semiconductor shares responded sharply. But the gap between a surging Nikkei and a weaker broader market showed that Tokyo’s rally still needs wider participation before it can be called durable.