investors weigh the global bonds selloff
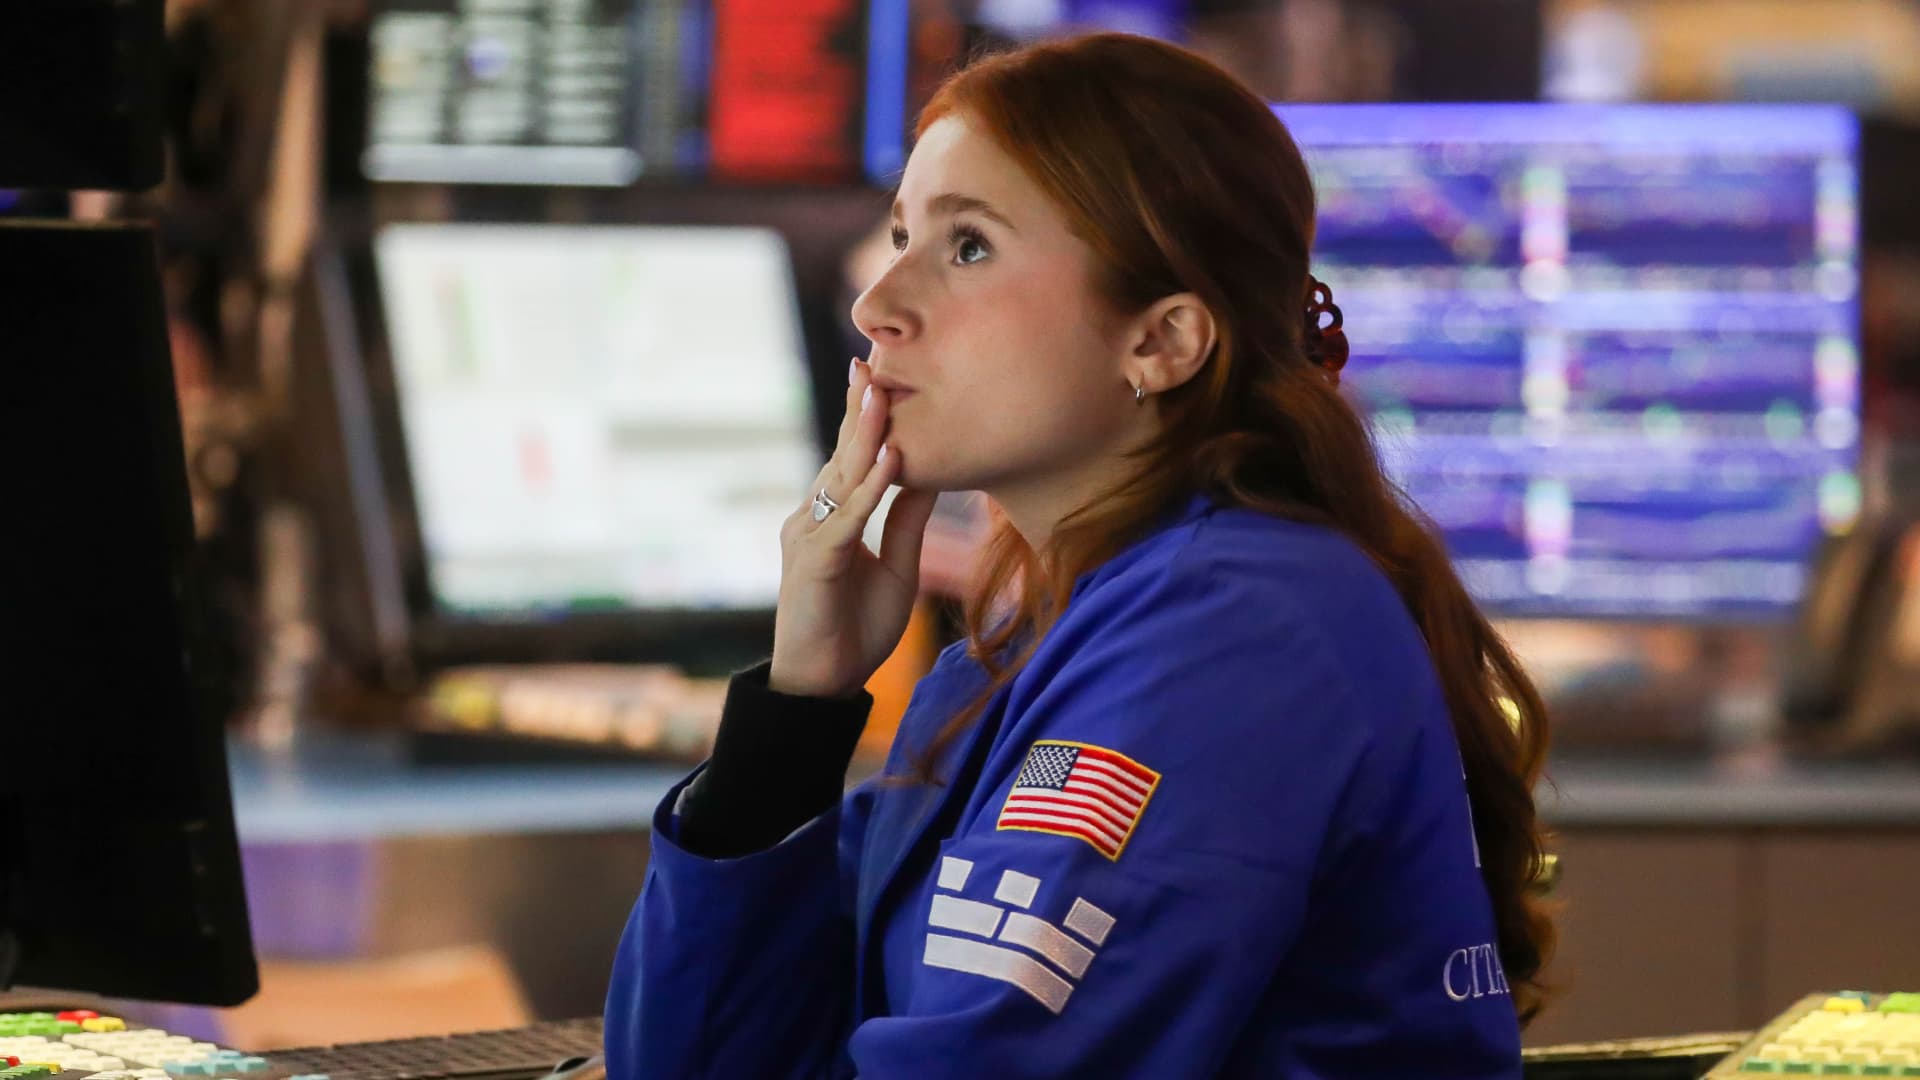
A trader works on the floor of the New York Stock Exchange (NYSE) in New York, US, on Wednesday, Aug. 12, 2026.
Michael Nagle | Bloomberg | Getty Images
U.S. Treasury yields inched higher on Friday as recent selling pressure intensified following hawkish Fed commentary and stronger-than-expected economic data.
The benchmark 10-year Treasury note was up more than 1 basis point to 5.175% after reaching its highest rate since June 2007 on Thursday. The 30-year Treasury bond was higher by less than 1 basis point at 5.47% after surging to levels not seen since 2004. The 2-year note yield was down less than 1 basis point at 4.891%.
One basis point is equal to 0.01%, and yields and prices move in opposite directions.
Investors weighed a global bond selloff this week as Japanese government bonds, U.K. gilts, German bunds and other eurozone bonds hit fresh highs. Eurozone and Japanese government bond yields edged lower on Friday.
Treasury yields have been driven higher by hawkish comments from Federal Reserve Governor Michael Barr, who said in a speech on Wednesday that “further policy adjustments” can be expected to bring inflation down to target. Other factors included stubbornly high oil prices and the purchasing managers’ index report hitting its highest level in more than four years.
Traders were last pricing in a 66% chance of a rate hike in October, according to the CME FedWatch tool.
On Friday, investors will watch the University of Michigan consumer sentiment report and durable goods data.
“Ahead, we think that there are enough rate hike fears discounted at this juncture, and certainly enough to take care of perceived inflation risks,” ING’s regional head of research for the Americas Padhraic Garvey and senior rates strategist Benjamin Schroeder wrote in a note on Friday.
“But, government bond yields are primed to remain under pressure on a pure debt dynamic theory, which translates into pressure for some re-widening in swap spreads, and especially in the 10yr area.”
“So far, Treasury Secretary Bessent’s buyback programme has in fact been successful in the sense that it was followed up by tighter swap spreads.”