Top 5 FD rates: Suryoday, Jana, Ujjivan, Equitas and AU SFB compared for key tenures
Fixed deposits (FDs) continue to be a popular option for investors looking for predictable returns without direct exposure to market volatility. However, FD interest rates can vary considerably depending on the bank and the tenure chosen. A bank offering a high headline rate may not necessarily offer the same rate for a one-, three- or five-year deposit.
In the current geopolitical environment, fixed deposits remain a popular option for investors nationwide seeking predictable returns without direct exposure to market volatility or capital loss risk.
According to data from Paisabazar, prominent small finance banks currently offer the highest rates among major lenders. Banks such as Suryoday Small Finance Bank, Jana Small Finance Bank and Ujjivan Small Finance Bank offer investors lucrative rates across different tenures.
Top 5 bank FD interest rates for 1, 3, 5 and 10 years
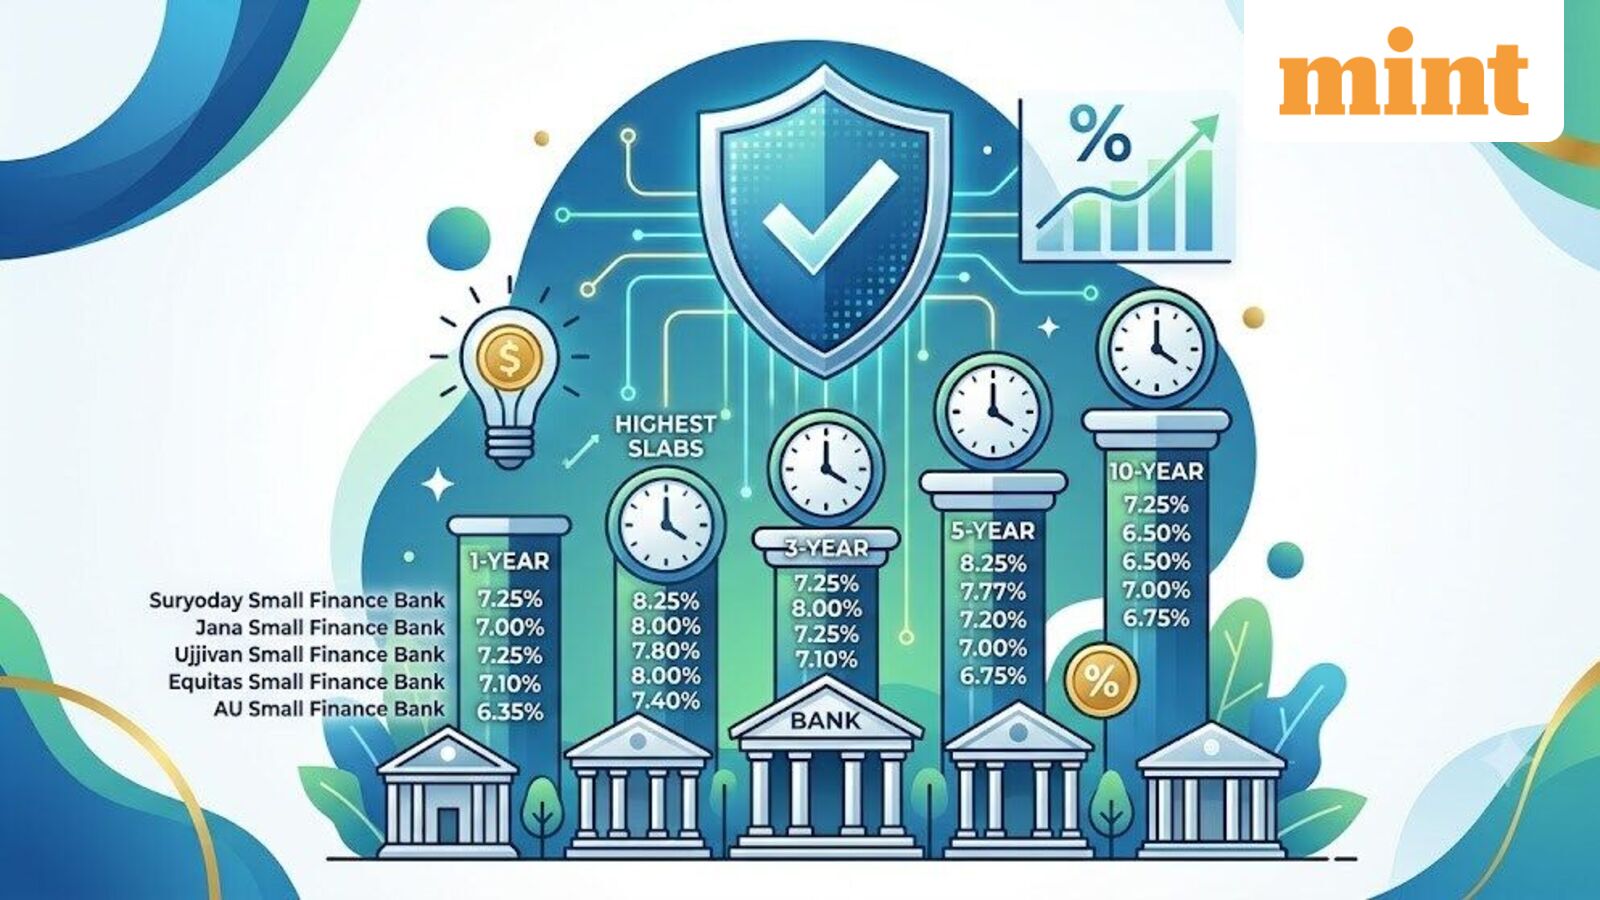
The following table shows the five banks with the highest rates in the supplied data across the selected tenures.
|
Bank |
Highest Slab | Tenure |
1-year |
3-year |
5-year |
10-year |
|---|---|---|---|---|---|---|
| Suryoday Small Finance Bank | 8.25% | 5 year | 7.25% | 7.25% | 8.25% | 7.25% |
| Jana Small Finance Bank | 8.00% | Above 2 years to 3 years | 7.00% | 8.00% | 7.77% | 6.50% |
| Ujjivan Small Finance Bank | 7.80% | 3 years 1 day to 3 years 6 months | 7.25% | 7.25% | 7.20% | 6.50% |
| Equitas Small Finance Bank | 8.00% | 3 years 1 day (Maxima FD) | 7.10% | 7.10% | 7.00% | 7.00% |
| AU Small Finance Bank | 7.40% | 30 months 1 day to 36 months | 6.35% | 7.40% | 6.75% | 6.75% |
Source: Paisabazaar.com. Interest rates as of 23 September 2026. Rates are per annum for regular depositors.
This table highlights why aspiring investors should compare rates based on their actual investment horizon, rather than simply choosing a lender based on its highest advertised FD rate.
The aim before locking in on any fixed deposits should be to first understand fixed deposits clearly, the implied rules, regulations, and taxes, and then opt for the best possible investment as per individual needs, in order to ensure absolute peace of mind later on.
For example, Jana Small Finance Bank’s highest rate currently is 8% for a tenure of 2 to 3 years. Still, this applies only to a specific tenure and not to all its FDs. Having clarity on this aspect is essential.
What about 2-year FDs?
For the same financial institutions, the two-year rates available as of September 2026 are: Suryoday Small Finance Bank 7.25%, Jana Small Finance Bank 7.30%, Ujjivan Small Finance Bank 7.65%, Equitas Small Finance Bank 7.55% and AU Small Finance Bank 7.00%.
As per Jana’s website, effective 6 August 2026, for a tenure of 367 days to 2 years, the applicable interest rate on domestic fixed deposits is 7.30%. Ujjivan’s official website lists 7.65% for a 2-year tenure, effective from 1 September 2026.
Equitas provides an annualised yield of 7.29% for a tenure of 2 years 1 day to 776 days, as per the data provided on its official website for investments of less than ₹3 crore. AU Small Finance Bank, on the other hand, offers a 7.29% annualised yield for tenures of 24 months 1 day to 30 months on amounts less than ₹3 crore. Suryoday’s published rate for a tenure of 2 years to less than 30 months is 7.45% annualised yield.
It is important to note that all rates discussed above are illustrative and subject to change. Before making any investments, it is advisable to check the official website for updated rates.
5 things to check before booking a fixed deposit
1. Check the exact tenure:
Do not rely only on the bank’s highest advertised rate. Check the rate applicable to the exact period for which you want to keep your money. Refer to the official website of the respective lending institution.
2. Check premature withdrawal rules:
An FD may allow premature closure, but the applicable interest rate can be lower, and a penalty may also apply. Understand all the rules and regulations before making any investment decisions.
3. Consider tax on interest:
FD interest is taxable according to the applicable income tax provisions. TDS may also apply when the prescribed threshold is crossed. FD taxation is another vital aspect to consider before locking in on any fixed deposit investments.
4. Check deposit insurance:
Eligible deposits with a bank are covered by Deposit Insurance and Credit Guarantee Corporation (DICGC) insurance up to ₹5 lakh per depositor per bank, including principal and interest.
5. Look at the payout option:
Investors should check whether they need regular interest payouts or prefer cumulative FDs, where interest is accumulated and paid at maturity. The choice can affect cash flow and the overall maturity amount.
Fixed deposit rates can change due to central bank moves and geopolitical developments. That is why the latest rate provided on the lending institution’s official website matters. All investors should therefore verify the latest rate, tenure, premature withdrawal rules, and other terms on the bank’s website before deciding to invest.
Disclaimer: FD interest rates are subject to change and may vary by tenure, deposit amount and customer category. Investors should verify the latest rates, terms, tax implications and premature withdrawal rules with the respective bank before investing.