Jane Fraser’s Citi Overhaul Faces Its Latest Earnings Test
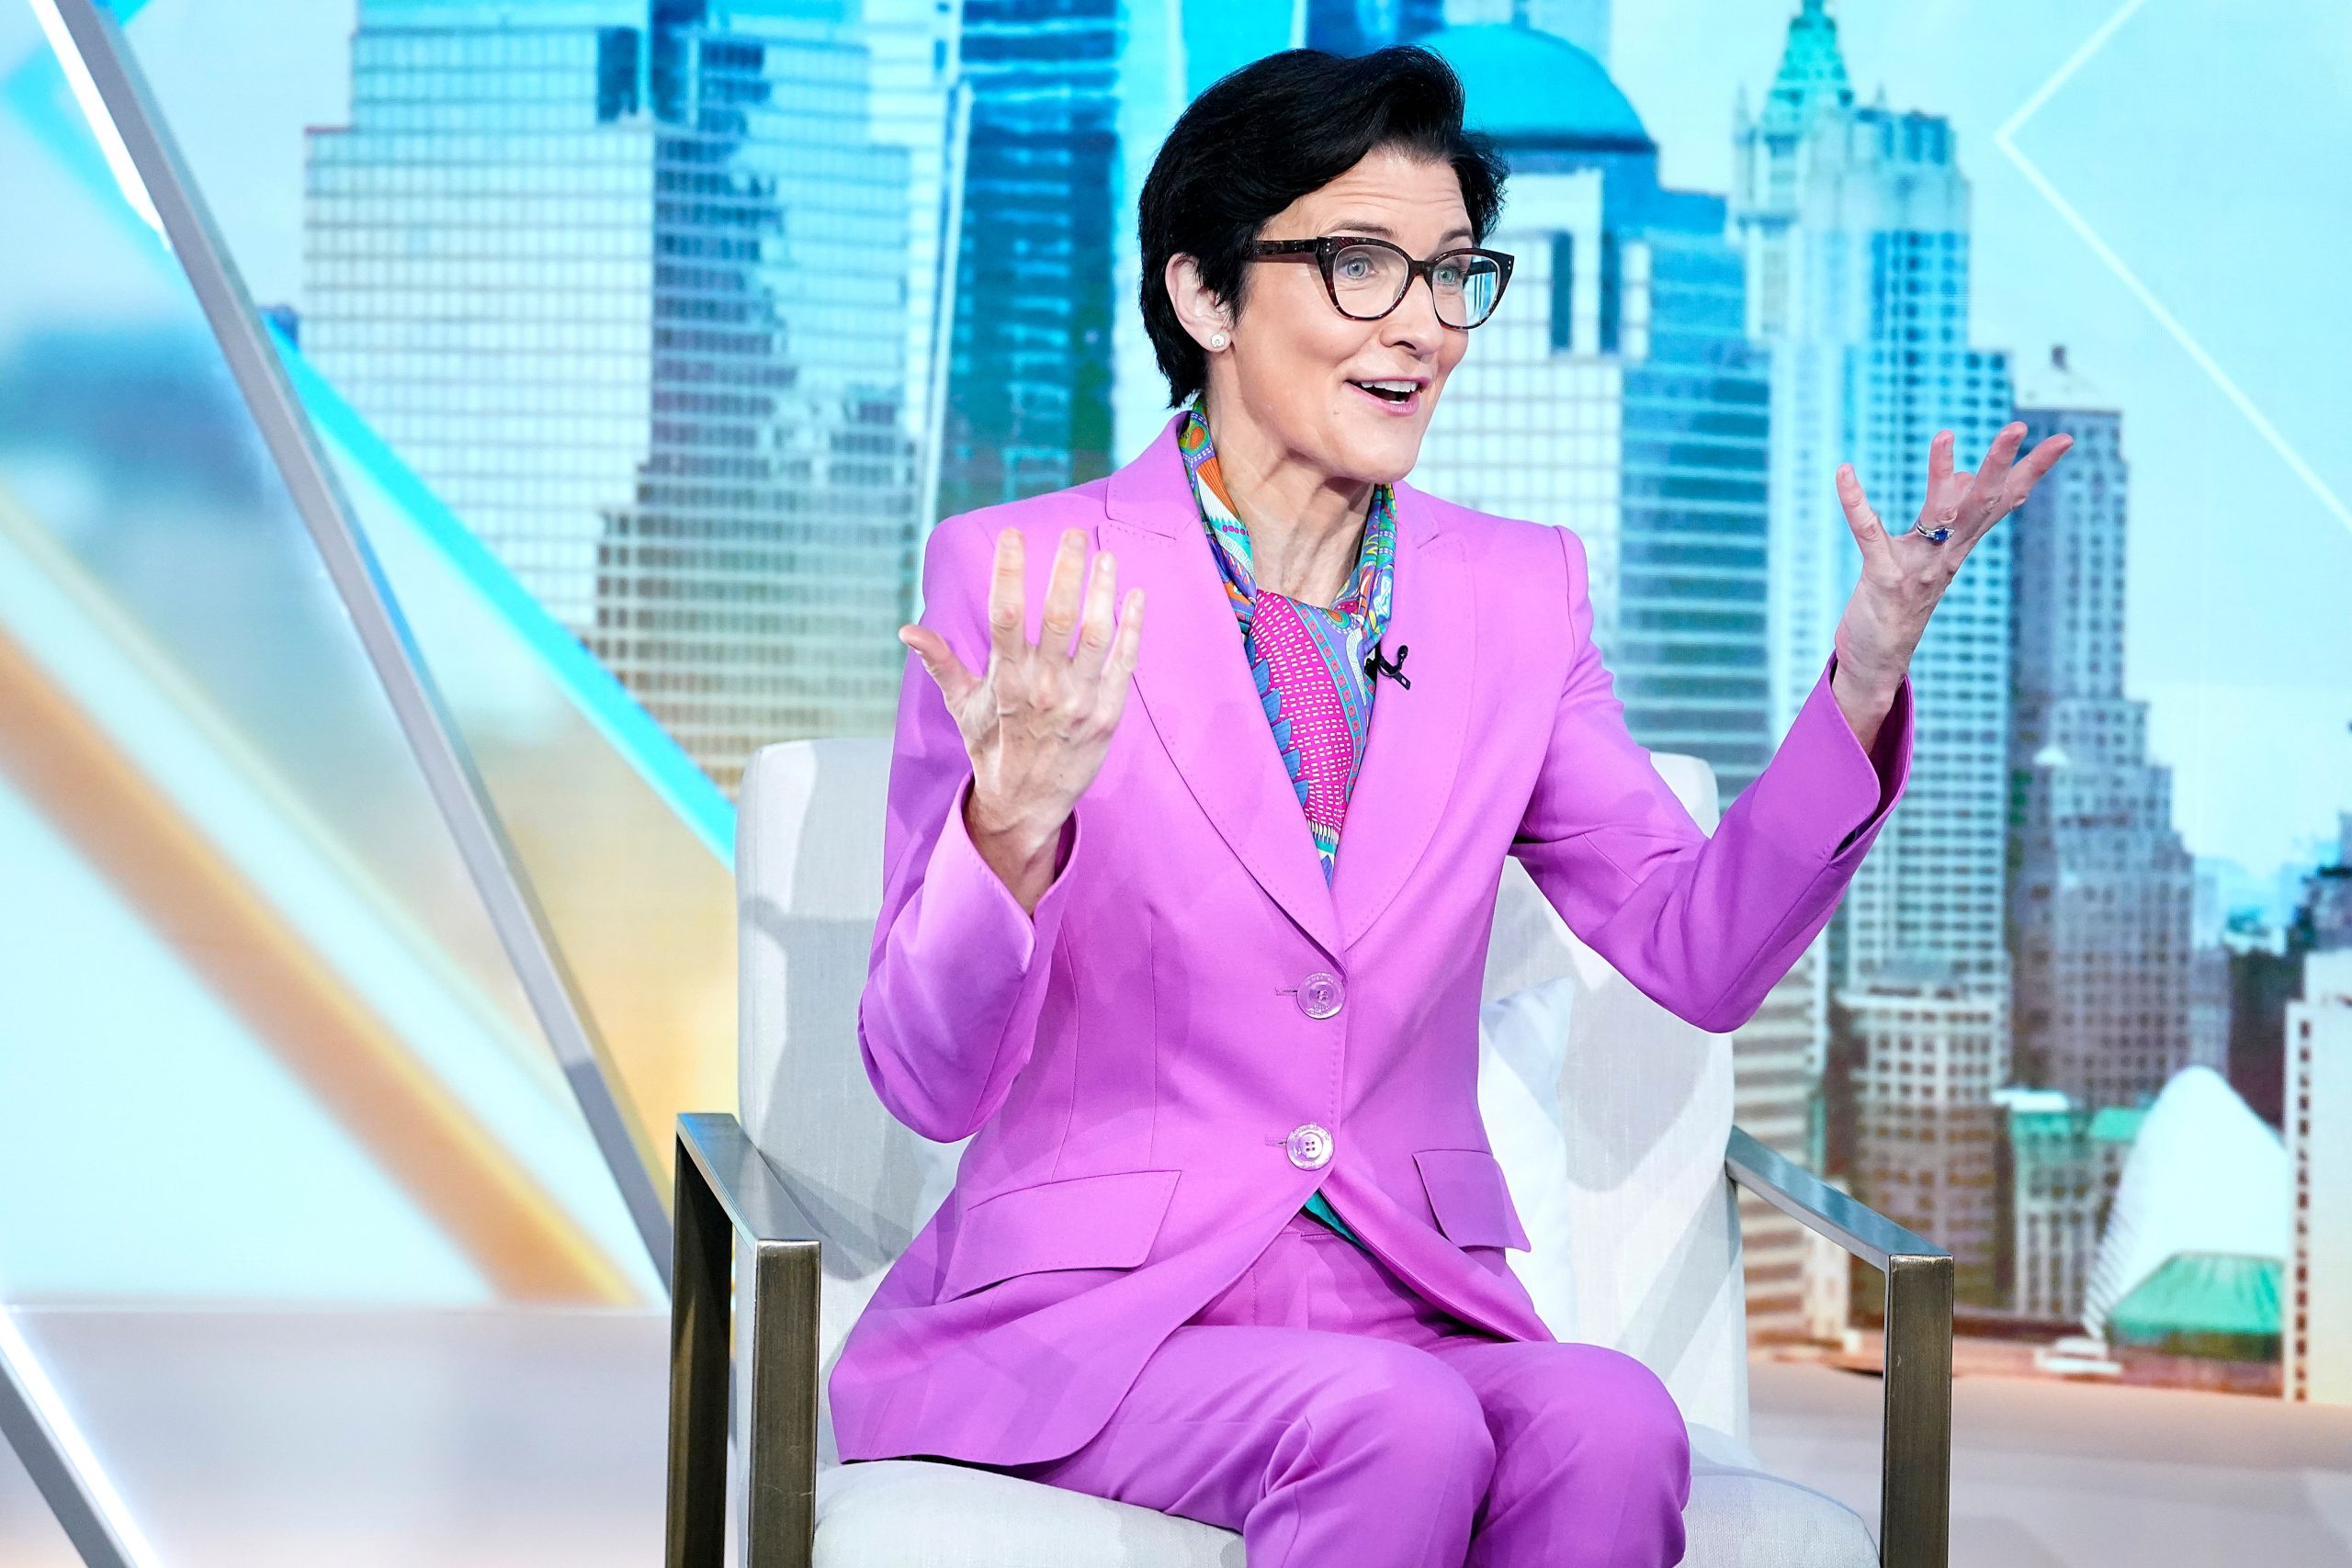
Citigroup CEO Jane Fraser has spent years both overhauling and simplifying one of Wall Street’s most complex global banks. Now, the numbers are beginning to show where the transformation is paying off and where the work remains unfinished. On its Oct. 13 earnings call, Citi reported $23.8 billion in third-quarter revenue, $5.2 billion in net income and an 11.5 percent return on tangible common equity (RoTCE), a measure of profit relative to shareholder capital after adjustments for intangible assets. On the call, Fraser said, “We delivered our best third quarter revenue in a decade.” But as investors assess her multiyear restructuring, the bigger question is if stronger revenue translates into sustainable returns across Citi’s five core businesses.
Fraser became the first woman to lead a major U.S. bank in 2021 following a difficult period for the bank. Citibank was fined $400 million by the Office of the Comptroller of the Currency for deficiencies in risk management and internal controls and Citi later reported a 43 percent decline in net income in 2020, driven by massive provisions for credit losses that the bank had to set aside to brace for the COVID-19 pandemic.
With a 5 percent decline in 2021 revenues, the outlook was not improving. On her first Investor Day as CEO in March 2022, Fraser introduced ambitious performance targets for Services, Markets, Banking, Wealth and U.S. Personal Banking, alongside plans to simplify the organization through heavy divestitures. Later in September 2023, she announced the biggest reorg of the bank in 20 years, setting out to reduce its hierarchy from 13 management levels to eight. This came in the wake of one of the most severe dealmaking droughts for global banking since the 2008 financial crisis. By January 2024, Citi had announced further plans to cut 20,000 jobs over several years.
While often sought for her expertise in getting Citi out of tricky situations during her 22-year tenure, such as navigating its U.S. mortgage business out of crisis following the 2008 financial downturn, Fraser’s goal as the CEO from the outset was to create a leaner organization with clearer accountability and stronger financial performance.
Services and Markets lead the turnaround
This quarter showed Services, which includes Treasury and Trade Solutions and Securities Services, as a standout. Revenue rose 15 percent year over year, while RoTCE reached 31.2 percent, above its objective of returns in the mid-20s across an economic cycle. The results suggest Citi is making progress in a business central to its global institutional banking franchise. Share repurchases are another part of Fraser’s capital strategy: Citi bought back $13.3 billion of shares through September, including $3 billion in the quarter, and announced a new $30 billion multiyear program. Those group-level repurchases should not be treated as the explanation for Services’ return; divisional returns also depend on the capital Citi assigns to each business.
Markets also delivered encouraging results. The division posted 6 percent revenue growth in the latest quarter and a 12.3 percent RoTCE. The challenge is now sustaining those returns as market conditions change.
On Oct. 23, Chinese regulators approved Citi’s plan to establish a wholly owned onshore securities company. The approval gives Fraser another avenue for growth, but does not mean the operation has opened.
Banking and Wealth show progress, but Cards lags
Citi’s Banking division reported 6 percent year-over-year revenue growth and a 19.2 percent RoTCE, up from 11.6 percent a year earlier. Scottish-born Fraser previously ran the Global Consumer Bank, a different business from today’s institutional Banking division.
Wealth revenue climbed 15 percent, but its 14.3 percent RoTCE remained below the 15 to 20 percent target for 2027–2028. Nevertheless, this represents a significant improvement from 7.8 percent in the third quarter of 2025. The division’s growth comes amid scrutiny following a sexual harassment lawsuit filed in January by former executive Julia Carreon against the bank involving wealth chief Andy Sieg. Carreon alleges Sieg subjected her to a “campaign of unrelenting and egregious sexual harassment, manipulation, and grooming,” according to court documents. Citi denies the allegations.
U.S. Consumer Cards was the weakest performer on revenue growth, remaining flat year over year at $4.7 billion. The business has undergone structural changes, with U.S. retail banking moved into Wealth and consumer cards established as a standalone franchise. Cards’ RoTCE reached 21.8 percent even as net income fell 8 percent, helped by a lower allocation of equity. The reorganization reflects Fraser’s effort to clarify accountability and improve returns, but the latest figures show that growth remains uneven across the bank.
A.I., risk and the next test
A.I. continues to be a core part of Citi’s strategy. During the 2026 Investor Day, Fraser spoke about Citi’s strategic focus on investing and implementing A.I. technologies for both the Wealth and Cards divisions, specifically customer acquisition, underwriting, servicing and engagement. During the Q3 earnings call, Mike Mayo with Wells Fargo Securities asked a question facing many banks: “Is Citi an A.I. victim or beneficiary?”
Fraser described tangible A.I. benefits in product development—noting a 30 to 40 percent increase in the speed of product launches—and firmwide efficiencies, stating “around 100 of our most manual processes have been or are being reengineered end-to-end, leveraging A.I. and automation.”
The bank plans to invest about $5 billion between 2026 and 2028 across technology, marketing, front-office talent and branch renovations. Citi Ventures invested in Anaconda, a development platform for building and operating A.I. at scale, in 2018. Citi Ventures now lists Anaconda among its exited portfolio companies.
While the bank has leveraged tech and made improvements since Fraser took on the CEO role, there have been setbacks. In 2024, U.S. regulators fined the bank $136 million for making “insufficient progress” resolving data management issues identified in 2020. Fraser said Citi had “been hardening our systems and running challenging and disruptive scenarios to stress test our defenses and our responses” during the earnings call.
Despite the strong third quarter, management cautioned that Markets revenue could be weaker in the fourth quarter, citing seasonality and the possibility of a larger sequential decline than last year’s roughly 20 percent drop. Chief Financial Officer Gonzalo Luchetti said the decline could be “possibly a bit more given the strong performance so far this year.”
Citi’s latest results suggest Fraser’s restructuring is gaining traction, particularly in Services, Markets and Banking. But with Cards growth flat, Wealth returns still below target and operational risks unresolved, the turnaround remains a work in progress. The real measure of Fraser’s success will be whether Citi can turn a strong quarter into sustained performance across the entire bank. http://gty.im/2295707864